 YouHuYou Components
CCL Supply Seen Tight Until 2029 as Glass Cloth Bottlenecks
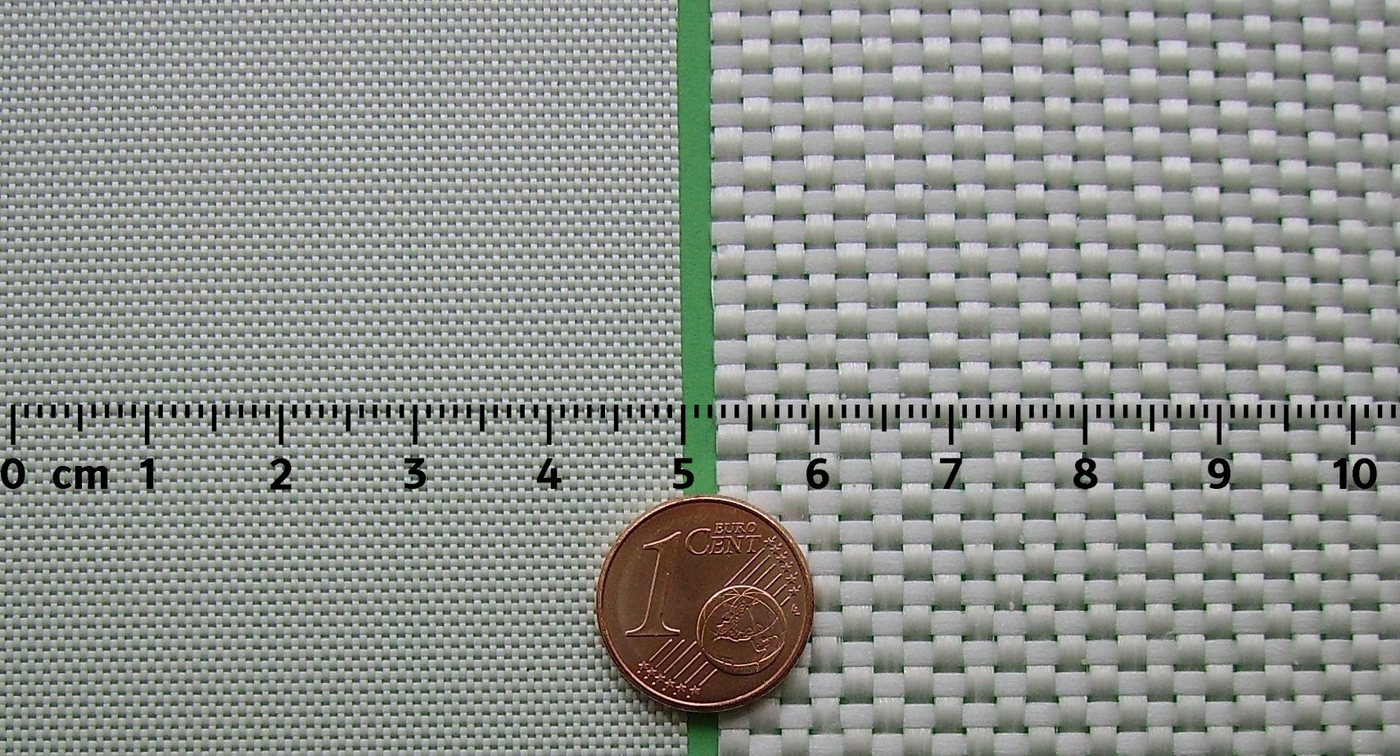
The copper-clad laminate market has passed another checkpoint. At the TPCA show in Taipei from 20-22 October, HSBC's channel checks found no laminate maker expecting supply and demand to balance before 2029, with AI-related demand growing faster than capacity can be added. Glass cloth, the woven reinforcement inside every laminate, is the binding constraint: specialty glass fabric is short, and glass cloth prices rose 18% in a single month according to industry commentary.
The price wave is rolling downstream. Kingboard, one of the world's largest laminate makers, raised all-thickness FR-4 by 10% at the end of August, then added 15% on new orders for thin-glass 2116-and-below prepreg from 13 October. Separate October commentary cites a 15% increase from another major laminate producer on CCL and prepreg. Copper prices near record levels add a floor under all of it.
Capacity cannot respond quickly. ABF substrate lamination equipment quotes lead times of two years or more, so new substrate plants approved now reach meaningful output around 2029. Material upgrades continue meanwhile: M10/M11-grade laminates, PTFE and hydrocarbon blends, mSAP processes for 12-14 layer any-layer HDI aimed at 800G and 1.6T optics, with HVLP5 copper foil ramping toward 2028.
For PCB buyers the implications are concrete. Standard FR-4 that quoted in two to three weeks now quotes six to eight; advanced low-loss laminates run 14 to 18 weeks. Quote validity on network and server boards has to shrink, and material escalation clauses belong in contracts for anything with a lead time past twelve weeks. Locking capacity with fabricators who hold upstream laminate allocations is now a selection criterion, not a preference. Expect PCB price lists to keep moving through Q4 as laminate suppliers pass costs through.